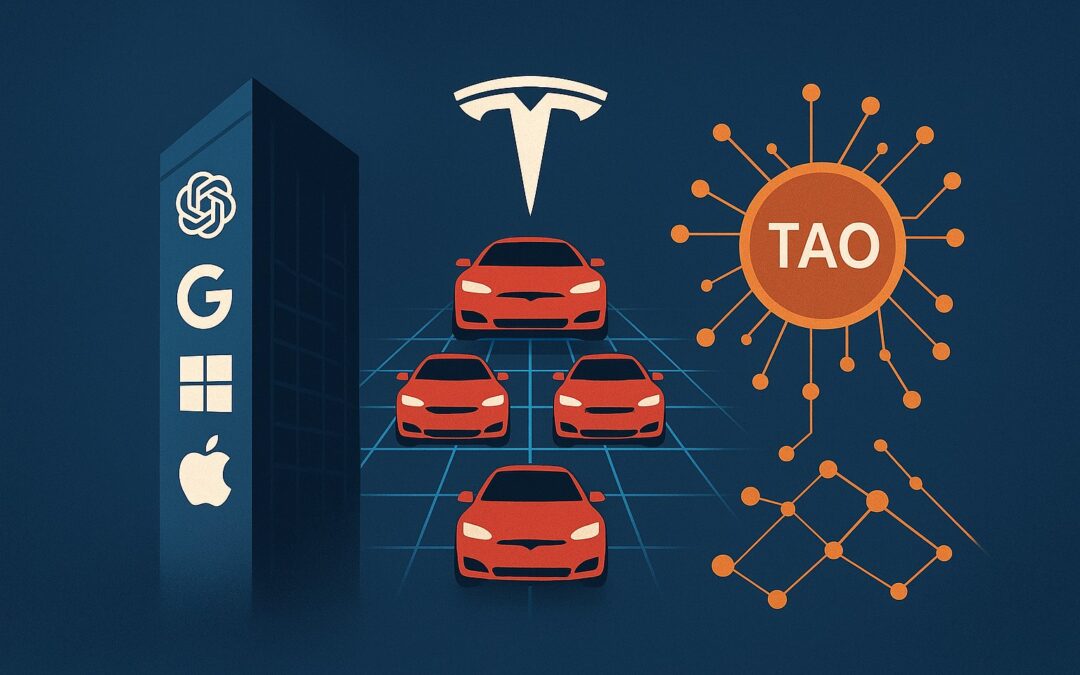
In our recent article on Bittensor’s TAO vs. centralized AI powerhouses, we explored a stark contrast: trillion-dollar data centers controlled by a handful of corporations versus an open, tokenized marketplace of distributed intelligence. But there may be a third contender quietly emerging — not in crypto, but in the garages, driveways, and streets of Tesla’s global fleet.
With millions of vehicles equipped with powerful GPUs for Full Self-Driving (FSD), Tesla possesses one of the largest untapped compute networks on the planet. If activated, this network could blur the line between centralized and decentralized AI, creating a new hybrid model of intelligence infrastructure.
Today’s Reality: Closed and Centralized
Right now, Tesla’s car GPUs are dedicated to autonomy. They process vision and navigation tasks for FSD, ensuring cars can see, plan, and drive. Owners don’t earn revenue from this compute; Tesla captures the value through:
FSD subscriptions ($99–$199 per month)
Vehicle sales boosted by AI features
The soon-to-launch Tesla robotaxi network, where Tesla takes a platform cut
In other words: the hardware belongs to the car, but the economic upside belongs to Tesla.
Musk’s Teasers: Distributed Compute at Scale
Elon Musk has hinted at a future where Tesla’s fleet could function as a distributed inference network. In principle, millions of idle cars — parked overnight or during work hours — could run AI tasks in parallel.
This would instantly make Tesla one of the largest distributed compute providers in history, rivaling even hyperscale data centers in raw capacity.
But here’s the twist: unlike Bittensor’s permissionless open market, Tesla would remain the coordinator. Tasks, payments, and network control would flow through Tesla’s centralized system.
The Middle Ground: Centralized Coordination, Distributed Hardware
If Tesla pursued this model, it would occupy a fascinating middle ground:
Not fully centralized – Compute would be physically distributed across millions of vehicles, making it more resilient than single-point mega data centers.
Not fully decentralized – Tesla would still dictate participation rules, workloads, and payouts. Owners wouldn’t directly join an open marketplace like Bittensor; they’d plug into Tesla’s walled garden.
This hybrid approach could:
Allow owners to share in the upside, earning credits or payouts for lending idle compute.
Expand Tesla’s revenue beyond mobility, turning cars into AI miners on wheels.
Position Tesla as both a transport company and an AI infrastructure giant.
Robotaxi + Compute: Stacking Revenue Streams
The real intrigue comes when you combine robotaxi revenue with distributed compute revenue.
A Tesla could earn money while driving passengers (robotaxi).
When idle, it could earn money running AI tasks.
For car owners, this would transform a depreciating asset into a self-funding, income-generating machine.
Challenges Ahead
Of course, this vision faces hurdles:
Energy costs – Would owners pay for the electricity used by AI tasks?
Hardware partitioning – Safety-critical driving compute must stay isolated from external workloads.
Profit sharing – Tesla has little incentive to give away margins unless it boosts adoption.
Regulation – Governments may view distributed AI compute as a new class of infrastructure needing oversight.
Tesla vs. Bittensor: A Different Future
Where Bittensor democratizes AI through open tokenized incentives, Tesla would likely keep control centralized — but spread the hardware layer globally.
Bittensor = open marketplace: Anyone can contribute, anyone can earn.
Tesla = closed network: Millions can participate, but only under Tesla’s rules.
Both models break away from the fragile skyscrapers of centralized AI superclusters. But their philosophies differ: Bittensor empowers contributors as stakeholders; Tesla would empower them as platform participants.
Centralized AI vs. Tesla Fleet Compute vs. Bittensor
Feature
Centralized AI (OpenAI, Google)
Tesla Fleet Compute (Potential)
Bittensor (TAO)
Control
Fully centralized, corporate-owned
Centralized by Tesla, distributed hardware
Decentralized, community-governed
Scale
Massive, but limited to data centers
Millions of vehicles worldwide
Growing global subnet network
Resilience
Vulnerable to single-point failures
More resilient via physical distribution
Highly resilient, peer-to-peer
Incentives
Profits flow to corporations
Owners may share revenue (compute + robotaxi)
Open participation, token rewards
Access
Proprietary APIs, restricted
Tesla-controlled platform
Permissionless, anyone can join
Philosophy
Closed & profit-driven
Hybrid: centralized rules, distributed assets
Open & meritocratic
Example Revenue
Cloud services, API subscriptions
FSD subs, robotaxi fares, possible compute payouts
TAO emissions, AI marketplace fees
The Horizon: A New Compute Economy?
If Tesla flips the switch, it could create a new middle path in the AI landscape — a centralized company orchestrating a physically decentralized fleet.
It wouldn’t rival Bittensor in openness, but it could rival Big Tech in scale. And for Tesla owners, it could mean their vehicles don’t just drive them — they also work for them, mining intelligence itself.
Artificial intelligence has become the infrastructure of modern civilization. From medical diagnostics to financial forecasting to autonomous vehicles, AI now powers critical systems that rival electricity in importance. But beneath the glossy marketing of Silicon Valley’s AI titans lies an uncomfortable truth: today’s AI is monopolized, centralized, and fragile.
Against this backdrop, a new contender is emerging—not in corporate boardrooms or trillion-dollar data centers, but in the open-source, blockchain-powered ecosystem of Bittensor. At the center of this movement is TAO, the protocol’s native token, which functions not just as currency but as the economic engine of a global, decentralized AI marketplace.
As Bittensor approaches its first token halving in December 2025—cutting emissions from 7,200 to 3,600 TAO per day—the project is drawing comparisons to Bitcoin’s scarcity-driven rise. Yet TAO’s story is more ambitious: it seeks to rewrite the economics of intelligence itself.
Centralized AI Powerhouses: Titans with Fragile Foundations
The Centralized Model Today’s AI landscape is dominated by a handful of companies—OpenAI, Google, Anthropic, and Amazon. Their strategy is clear: build ever-larger supercomputing clusters, lock in data pipelines, and dominate through sheer scale. OpenAI’s Stargate project, a $500 billion bet on 10 GW of U.S. data centers, epitomizes this model.
But centralization carries steep costs and hidden risks:
Economic Barriers – The capital required to compete is astronomical. Training frontier models like GPT-4 costs upward of $100 million, with infrastructure spending in the billions. This effectively locks out smaller startups, concentrating innovation in a few corporate hands.
Data Monopoly – Big Tech controls the largest proprietary datasets—Google’s search archives, Meta’s social graph, Amazon’s consumer data. This creates a closed feedback loop: more data → better models → more dominance. For the rest of the world, access is limited and increasingly expensive.
Censorship & Control Risks – Centralized AI is subject to corporate and political agendas. If OpenAI restricts outputs or Anthropic complies with government directives, the flow of intelligence becomes filtered. This risks creating a censored AI ecosystem, where knowledge is gated by a few powerful actors.
Systemic Fragility – The model resembles the financial sector before 2008: a handful of players, each “too big to fail.” A catastrophic failure—whether technical, economic, or regulatory—could ripple through industries that rely on these centralized AIs. Billions in stranded assets and disrupted services would follow.
The Decentralized Alternative Bittensor flips this script. Instead of pouring capital into singular mega-clusters, it distributes tasks across thousands of nodes worldwide. Intelligence is openly contributed, scored, and rewarded through the Proof of Intelligence mechanism.
Where centralized AI is vulnerable to censorship and collapse, Bittensor is adaptive and antifragile. Idle nodes can pivot to new tasks; contributors worldwide ensure redundancy; incentives drive continual innovation. It’s less a fortress and more a living, distributed city of intelligence.
📊 Centralized AI vs. Bittensor (TAO)
Category
Centralized AI (OpenAI, Google, Anthropic)
Decentralized AI (Bittensor TAO)
Infrastructure
Trillion-dollar data centers, tightly controlled
Distributed global nodes, open access
Cost of Entry
$100M+ to train frontier models, billions for infra
Anyone can contribute compute/models
Data Ownership
Proprietary datasets, hoarded by corporations
Open, merit-based contributions
Resilience
Single points of failure, fragile to outages/regulation
Adaptive, antifragile, redundant nodes
Governance
Corporate boards, shareholder-driven
Token-staked community governance
Censorship Risk
High – subject to political & corporate pressure
Low – distributed contributors worldwide
Innovation
Innovation bottlenecked to few elite labs
Permissionless, global experimentation
Incentives
Profits concentrated in Big Tech
Contributors rewarded directly in TAO
Analogy
Skyscraper: tall but fragile
City: distributed, adaptive, resilient
The Mechanics of TAO: Scarcity Meets Utility
Like Bitcoin, TAO has a fixed supply of 21 million tokens. Its functions extend far beyond speculation:
Fuel for intelligence queries – Subnet tasks are priced in TAO.
Staking & governance – Token holders shape the network’s evolution.
Incentives for contributors – Miners and validators earn TAO for producing valuable intelligence.
Upgrades like the Dynamic TAO (dTAO) model tie emissions directly to subnet performance, rewarding merit over hype. Meanwhile, EVM compatibility unlocks AI-powered DeFi, merging decentralized intelligence with tokenized finance.
Already, real-world applications are live. The Nuance subnet provides social sentiment analysis, while Sturdy experiments with decentralized credit markets. Each new subnet expands TAO’s utility, compounding its value proposition.
The Investment Case: Scarcity, Adoption, and Network Effects
Bittensor’s bullish thesis rests on three pillars:
Scarcity – December’s halving introduces hard supply constraints.
Adoption – Over 50 subnets are already operational, each creating new demand for TAO.
Network Effects – As contributors join, the intelligence marketplace becomes more valuable, drawing in further participants.
Institutional validation is mounting:
Europe’s first TAO ETP launched on the SIX Swiss Exchange.
Firms like Oblong Inc. are already acquiring multimillion-dollar TAO stakes.
Price forecasts reflect this momentum, with analysts projecting $500–$1,100 by year-end 2025 and potential long-term valuations above $7,000 if Bittensor captures even a sliver of the $1 trillion AI market projected for 2030.
Decentralized AI Rivals: How TAO Stacks Up
Bittensor is not alone in the decentralized AI (DeAI) space, but its approach is distinct:
While Render and Akash provide raw compute, Bittensor adds the intelligence layer—a marketplace for actual cognition and learning. Community consensus is clear: the others could function as subnets within Bittensor’s architecture, not competitors to it.
Historical Parallel: From Mainframes to Decentralized Intelligence
Technology has always moved from concentration to distribution:
Mainframes (1960s–70s): Computing power locked in corporate labs.
Personal Computing (1980s–90s): PCs democratized access.
Cloud (2000s–2020s): Centralized services scaled globally, but reintroduced dependency on corporate monopolies.
Decentralized AI (2020s–): Bittensor represents the next shift, distributing intelligence itself.
Just as the internet shattered the control of centralized telecom networks, decentralized AI could dismantle the stranglehold of Big Tech’s AI empires.
Risks: The Roadblocks Ahead
No revolution comes without obstacles.
Validator concentration threatens decentralization if power clusters among a few players.
Speculative hype risks outpacing real utility, especially as crypto volatility looms.
Regulation remains a wildcard; governments wary of ungoverned AI may impose restrictions on DeAI protocols.
Still, iterative upgrades—like dTAO’s merit-based emissions—are steadily addressing these concerns.
The Horizon: TAO as the Currency of Intelligence
Centralized AI may dominate headlines, but its vulnerabilities echo the financial sector’s “too big to fail” problem of 2008. Bittensor offers an alternative—a decentralized bailout for intelligence itself.
If successful, TAO won’t just be a speculative asset. It will function as the currency of thought, underpinning a self-sustaining economy where intelligence is bought, sold, and improved collaboratively.
The real question isn’t whether decentralized AI will rise—it’s who will participate before the fuse is lit by the halving.
The crypto landscape for 2025–2026 is shaping up to be a battle between established giants like Ethereum and Solana, and fast-rising challengers like Hyperliquid (HYPE). With the launch of HyperEVM, Hyperliquid has the chance to expand from its stronghold in perpetual trading into broader DeFi, Real-World Assets (RWAs), and potentially rival Solana in transaction speed. But how realistic is this vision?
1. HyperEVM: The Gateway to DeFi Expansion
Until now, Hyperliquid has been synonymous with decentralized perpetual trading. It dominates the sector with more than 70% market share, $1.6 trillion in cumulative trading, and over $90M monthly revenue. But the introduction of HyperEVM changes the game.
EVM compatibility means Ethereum-based apps can easily port over.
Zero-gas transactions and sub-second finality give developers and users a frictionless experience.
Liquidity incentives tied to HYPE’s buyback and burn model could bootstrap early adoption.
Outlook: With these advantages, HyperEVM could capture 5–15% of DeFi market share within 1–2 years, pulling liquidity from smaller Ethereum L2s and even attracting new native projects.
2. RWAs: The Tougher Frontier
Real-World Assets are the hottest institutional narrative in crypto, with tokenized treasuries, bonds, and real estate projected to reach $10T+ by 2030.
Ethereum leads this space with BlackRock’s BUIDL fund, MakerDAO, and Centrifuge.
Hyperliquid’s zero-gas and ultra-fast settlement could appeal to smaller issuers and crypto-native RWA protocols.
The challenge is institutional trust and partnerships — Ethereum already has a head start with major financial players.
Outlook: Hyperliquid can carve out niches in crypto-native RWAs, but competing head-to-head with Ethereum’s institutional moat is unlikely in the near term.
3. Speed Wars: Hyperliquid vs. Solana
One of the boldest claims from Hyperliquid is its ability to process 200,000 TPS with 0.2s latency using HyperBFT consensus. On paper, this surpasses Solana’s benchmarks:
Caveat: Many of Hyperliquid’s performance metrics come from high-frequency order processing rather than general-purpose DeFi activity. Solana, meanwhile, has an established NFT, gaming, and memecoin culture that generates organic demand for blockspace.
Outlook: Hyperliquid can rival or even exceed Solana technically. But ecosystem demand — not raw TPS — will decide the winner. Solana has culture; Hyperliquid needs its own beyond perps.
4. Data-Driven Comparison
Feature
Ethereum (ETH)
Solana (SOL)
Hyperliquid (HYPE)
Strengths
Institutional RWAs, L2 ecosystem
High-speed, NFT & retail adoption
Dominates perps, zero-gas DeFi hub
Market Cap (FDV)
$400B+
$100–120B
~$40B
Revenue (annualized)
~$3.5–4B
~$250–300M
~$1.1B
P/S Multiple
100–120x
330–400x
35–40x
TPS / Latency
~30 TPS / ~12s
~1,500 sustained / ~400ms block time
Claims 200k TPS / ~0.2s latency
Cultural Edge
Institutions, DeFi, RWAs
NFTs, gaming, memecoins
Perps culture, DeFi traders
5. Where Hyperliquid Could Dominate
Each chain has carved its niche:
Ethereum: Institutional RWA + L2 hub.
Solana: High-speed retail + NFT culture.
Hyperliquid: Zero-gas perps + DeFi liquidity hub.
If Hyperliquid successfully expands with HyperEVM and builds a broader community around DeFi apps, it could become the go-to chain for active trading, leveraged finance, and liquidity aggregation.
Conclusion
Hyperliquid is not just another L1 experiment. With HyperEVM, it has the tools to:
Pull in DeFi projects from Ethereum.
Capture crypto-native RWA niches.
Rival Solana in transaction throughput.
The question is whether Hyperliquid can grow its ecosystem demand and cultural identity to match its technical prowess. If it does, 2025–2026 could see Hyperliquid evolve from a perps powerhouse into a full-spectrum DeFi chain capable of standing beside Ethereum and Solana.
Ready to Experience Hyperliquid?
Discover the next level of decentralized trading with Hyperliquid. Discover Hyperliquid!
MicroStrategy has transformed itself from a software company into the world’s largest publicly traded Bitcoin proxy. Through its financing arm Strategy, it now offers investors new ways to gain exposure to Bitcoin — each with its own mix of risks and rewards.
How It Works
Every time MicroStrategy or Strategy raises capital — by issuing common stock (MSTR), preferred stock (STRC), or convertible debt — the proceeds are used to buy more Bitcoin.
This creates a flywheel:
Bitcoin rises → balance sheet grows → easier to issue more securities.
Bitcoin falls → balance sheet shrinks → obligations get harder to sustain.
Both MSTR and STRC holders are diluted each time new securities are sold. What differs is how they benefit from Bitcoin’s moves.
Breaking Down the Products
MSTR (common stock): Equity ownership. Gains are leveraged to Bitcoin’s price, but dilution reduces your share.
STRC (preferred stock): Pays ~9% annual dividend. Works like a bond — you don’t own the company, you just expect income. Returns are capped, and dividends depend on Strategy’s ability to fund them.
BTC ETF: Pure Bitcoin exposure. No dilution, no yield, but transparent and liquid.
Physical Bitcoin (self-custody): The purest exposure. No counterparty risk, no dilution, no engineering. But it requires discipline: securing private keys, protecting seed phrases, and resisting the temptation to offload custody to third parties. For long-term believers, this is the safest and most sovereign way to hold Bitcoin.
Where Does STRC’s Yield Come From?
The ~9% yield on STRC doesn’t come from “Bitcoin interest” — it’s financed by Strategy’s capital structure. Dividends can be paid in three ways:
From operating cash flows (MicroStrategy still sells software and services, though this is modest compared to Bitcoin exposure).
From new debt or equity issuance, which brings in fresh capital.
From Bitcoin appreciation, allowing Strategy to borrow against or sell Bitcoin at higher prices.
In a sustained downturn, these sources shrink. If Bitcoin falls far enough, Strategy may need to sell Bitcoin to cover obligations. That creates a potential feedback loop: selling pressure pushes Bitcoin down further, which weakens the balance sheet, forcing more selling.
This loop is the key fragility of the model. Unlike a Bitcoin ETF or self-custody, STRC’s stability depends not just on Bitcoin’s long-term direction, but also on Strategy’s ability to continually finance dividends in rough markets.
Data Snapshot (5-Year Simulation)
Starting BTC price: $116,000
BTC Future Price
Direct BTC
MSTR (leveraged)
STRC (dividends + principal)
$30,000
–74%
–90%+
~+$45k total income
$60,000
–48%
–70%
~+$45k total income
$120,000
~0%
~0%
~+$45k total income
$200,000
+72%
+152%
~+$45k total income
Takeaway:
STRC looks stable — but only if Strategy can keep paying.
MSTR swings harder than Bitcoin in both directions.
ETFs give clean exposure.
Holding Bitcoin directly gives you full upside with no dilution, but puts security in your hands.
Lessons from History
Financial engineering is not new. Past examples — mortgage-backed securities (2008) or structured notes in Europe (2010s) — looked stable until the underlying assets wobbled.
STRC isn’t a scheme — it’s backed by real Bitcoin. But its yield depends entirely on Bitcoin’s long-term path, and new issuances dilute existing holders
ETF: The “Endgame”?
The arrival of spot Bitcoin ETFs brings institutional legitimacy. For many investors, ETFs will be the endgame: simple, regulated, and transparent.
But for others:
MSTR → leverage for amplified gains (and amplified risks).
STRC → yield for those who want Bitcoin-linked income.
Physical Bitcoin → sovereignty for those who can manage self-custody.
Bottom Line
Strategy’s products are clever financial engineering — not scams, but not free of fragility either. Investors must remember: whether through MSTR, STRC, ETFs, or cold storage wallets, all paths ultimately depend on one factor.
If Bitcoin rises, every version of the strategy shines. If it falls, every version suffers — only in different ways.
Since February 2025, President Trump’s escalating tariff announcements have sent shockwaves through global markets. From initial levies on Canada and Mexico to sweeping tariffs affecting 57 countries, each policy shift has triggered significant volatility across equities, cryptocurrencies, and commodities.
Below is a timeline of key tariff-related events, market reactions, and the BTC price swings they triggered.
📆 Timeline of Trump Tariff Announcements vs Market Reactions
Here’s a snapshot of the most volatile days:
📅 Date
🗞️ Announcement
📉 S&P 500
₿ Bitcoin
🪙 Altcoins
🏆Gold
Feb 1
25% tariffs on Canada/Mexico; 10% on China
N/A
-3.0%
-12.0% (XRP, SOL, ETH hardest hit)
~$2,540
Mar 12
25% global steel/aluminum tariffs
-1.5%
-1.5%
-3.0%
~$2,780
Apr 2
Emergency tariffs: 10–54% on 57 countries
-3.4%
-10.0%
-25.0% (market cap halved)
~$3,167
Apr 3–4
Enforcement begins, then recession panic. Aditional tariffs on Israel and Vietnam
-4.88% → -5.97%
-5.0%
-10% to -15% more (Coinbase down 7.7%)
~$3,004
Apr 9
Tariff pause; 25% auto tariffs (China at 125%) sparks rally
+9.52%
+8.0%
+10.0% (XRP, SOL rebound strongest)
~$3,245
Apr 10
Market digests pause; no new announcement
-2.5%
-4%
-5%
~$3,180
Apr 14
Exemptions for electronics (Apple, etc.)
+0.79%
+1.5%
+3.0% (tech-linked alts benefit e.g., Apple shares)
~$3,212
Apr 22
Gold hits record high amid market uncertainty
+0.5%
+2.0%
+4.0%
$3,500 (intraday)
Note: Gold and silver prices are approximate and based on available data.
📊 Visualizing the Chaos
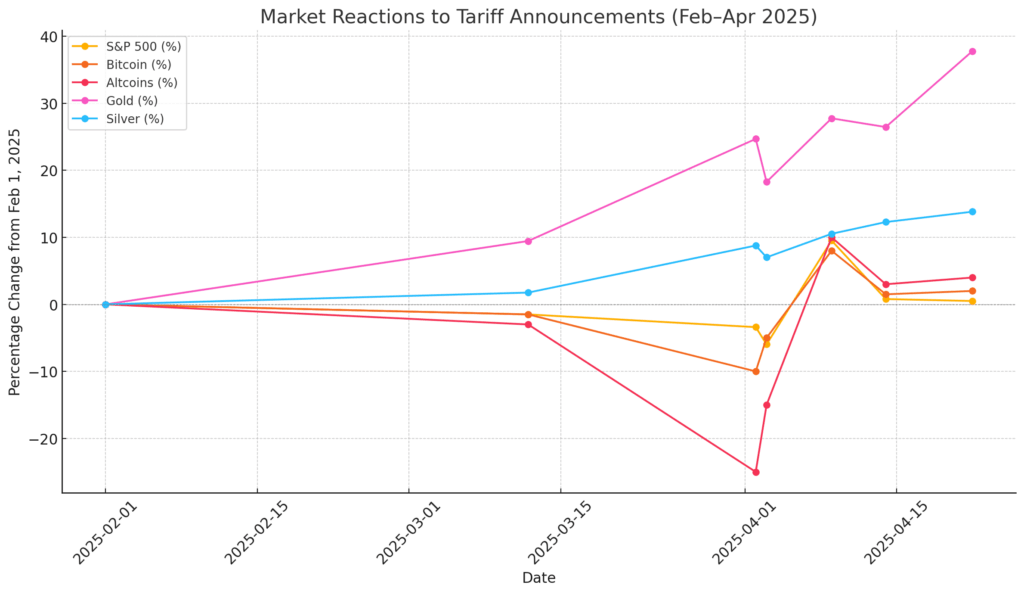
The chart below shows the parallel trajectory of the S&P 500 and Bitcoin through the turbulence of Trump’s trade moves:
🔶 Bitcoin declined across most announcements until the April 9 pause triggered a sharp relief rally.
🔷 The S&P 500 saw sharper daily percentage drops than Bitcoin, highlighting the broad risk-off sentiment.
🟡 Gold held its ground — and then rallied hard — as safe-haven demand returned.
🪙 Altcoins exhibited the most volatility, with sharp losses and rebound attempts tied to macro sentiment.
What This Shows Us
🧯 Crypto ≠ Hedge (At Least Not Short-Term)
Bitcoin mirrored equities more often than not, suggesting that macro fears — like sudden tariff escalations — continue to pull crypto into broader market turbulence.
🎭 Policy Uncertainty Wrecks Confidence
Markets don’t just fear bad news — they fear unpredictability. The Trump strategy of announcing, delaying, then doubling down created persistent anxiety, which hit all asset classes hard.
🕊️ Pause = Relief
The April 9 policy pause was met with immediate risk-on appetite. Stocks, Bitcoin, and altcoins all posted strong gains — highlighting just how starved markets were for clarity.
🧪 Asset Highlights
Altcoins & XRP: Highly sensitive to macro narratives. Saw deep losses on Feb 1 and Apr 2, but also led in rebounds post-pause.
SOL: Frequently among the hardest-hit but also one of the fastest to recover, especially in bullish pockets like Apr 9–14.
Apple & Tech Stocks: Benefited from exemptions. Their recovery lifted tech-linked altcoins and improved sentiment across risk assets.
Ondo Finance: Outperformed many majors during volatility. The RWA narrative continued to resonate as TradFi institutions looked for yield-bearing digital instruments.
Coinbase (COIN): Declined sharply on Apr 3 as fears around U.S. policy spillover weighed heavily on publicly traded crypto firms.
🔭 Where Do We Look From Here?
1. Macro-Driven Markets Are the New Normal
Gone are the days when crypto danced to its own beat. The correlation between equities and crypto is tighter than ever — especially in the face of unpredictable geopolitical and trade policies. When Trump speaks, crypto bleeds, just like stocks.
2. BTC is Resilient, Alts Are Risk-On Bets
Holding alts continues to reflect high-volatility exposure to global risk sentiment. Bitcoin may bounce back after 10% drops, but alts often need coordinated bull runs or macro relief to fully recover.
3. Narrative Is Everything
Projects like Ondo and tokenized real-world asset (RWA) platforms showed signs of strength even during the turbulence. Safe yield and TradFi-linked infrastructure might emerge as the next defensive play in crypto.
🧩 Lessons Learned
Announcements punch first — policy plans are often priced in before they take effect.
Delays still sting — the Feb 1 to Mar 4 window saw markets fall before the actual implementation.
Watch for pivots — April 9’s sudden pause reversed days of damage.
Diversification matters — BTC declined 3–10%; alts dropped 10–30%. Risk tolerance is more important than ever.
🧭 Navigating the Tariff Pause
The current 90-day pause on escalations gives markets some breathing room. But if this cycle has shown anything, it’s that traders today need to be macro-aware, responsive, and measured. Crypto is no longer isolated — it’s macro-attached.
🌅 Is a Bitcoin Decoupling on the Horizon?
While Bitcoin has largely traded like a risk asset during recent macro shocks, its long-term fundamentals — such as fixed supply, decentralized settlement, and increasing adoption by sovereigns and institutions — may lay the groundwork for future decoupling. As traditional markets face growing debt burdens and monetary interventions, Bitcoin’s digital scarcity could start to resonate more like gold than tech — especially if the demand for neutral, self-custodied assets rises in politically volatile environments.
🏆 Gold: The Traditional Safe Haven
Gold’s climb from ~$2,540 to $3,500 during this window reinforces its role as a traditional hedge. But it’s worth noting that the paper-to-physical gold ratio (sometimes exceeding 100:1) raises questions about how accurately markets price real demand — especially in a crisis. Structural fragility could still impact how gold performs in future market stress.
🥈 Silver: The Underestimated Play
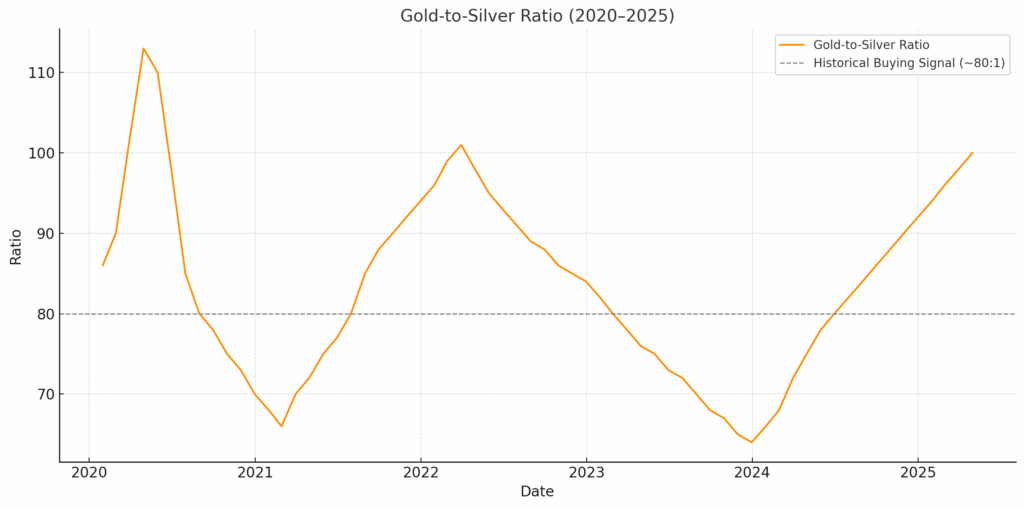
While less discussed, silver posted meaningful gains in tandem with gold. With gold peaking, one key metric to watch closely is the gold-to-silver ratio — currently near historically high levels. When this ratio stretches (e.g., 80:1 or higher), it has often marked strong buying windows for silver. Historically, silver tends to play catch-up in late-stage commodity rallies, offering outsized upside when capital flows rotate from gold into undervalued metals.
Here’s a historical chart of the Gold-to-Silver ratio from 2020 to 2025, highlighting how we’re again near the 80–100 range — a zone that has often preceded strong silver rallies.
To provide the best experiences, we use technologies like cookies to store and/or access device information. Consenting to these technologies will allow us to process data such as browsing behaviour or unique IDs on this site. Not consenting or withdrawing consent, may adversely affect certain features and functions.
Functional
Always active
The technical storage or access is strictly necessary for the legitimate purpose of enabling the use of a specific service explicitly requested by the subscriber or user, or for the sole purpose of carrying out the transmission of a communication over an electronic communications network.
Preferences
The technical storage or access is necessary for the legitimate purpose of storing preferences that are not requested by the subscriber or user.
Statistics
The technical storage or access that is used exclusively for statistical purposes.The technical storage or access that is used exclusively for anonymous statistical purposes. Without a subpoena, voluntary compliance on the part of your Internet Service Provider, or additional records from a third party, information stored or retrieved for this purpose alone cannot usually be used to identify you.
Marketing
The technical storage or access is required to create user profiles to send advertising, or to track the user on a website or across several websites for similar marketing purposes.